The Corporate Migration Dividend: How Fortune 500 Expansions Into India's Secondary Cities Are Creating a Land Investment Inflection Point
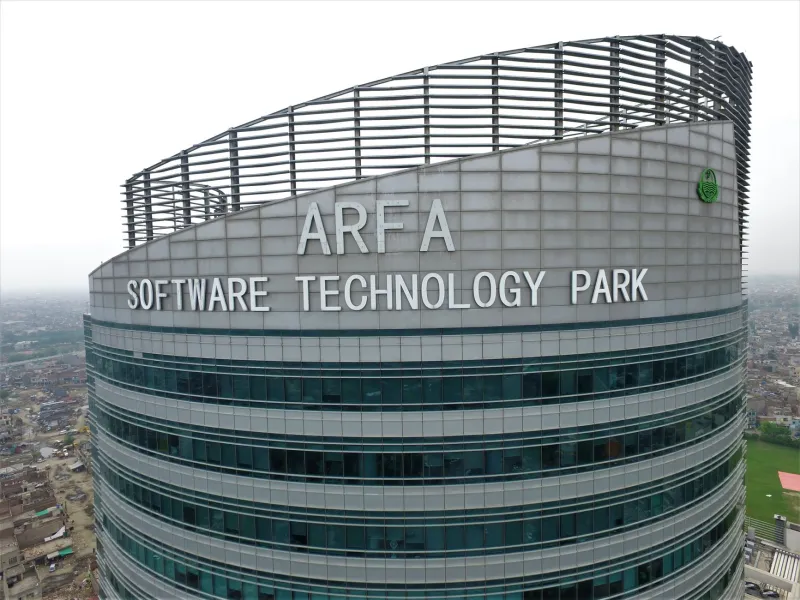
There is a particular kind of investment opportunity that reveals itself not in earnings reports or press releases, but in the quiet accumulation of small, unremarkable decisions made by corporate real estate directors, HR executives, and operations planners. These decisions rarely make headlines. They show up instead in building permit applications, in the LinkedIn profiles of relocated employees, and in the lease agreements signed in business parks that most investors have never heard of.
Right now, a version of this quiet revolution is unfolding across India's secondary cities — and the land investment implications are substantial.
The Economics Behind the Exodus
The logic driving Fortune 500 companies toward India's Tier-2 cities is not complicated, but its consequences are frequently underestimated. Bengaluru, Hyderabad, and Pune — the traditional anchors of India's technology and back-office economy — have spent two decades absorbing corporate demand with impressive capacity. But that absorption has come at a cost. Office rents in Bengaluru's outer ring road corridor have increased by more than 40 percent over the past five years. Attrition rates among technology professionals in primary metros regularly exceed 25 percent annually. Commute times in Hyderabad's Gachibowli district now rival those of midtown Manhattan during peak hours.
The arithmetic for a CFO evaluating operational footprint has shifted. A mid-sized technology operations center that costs $8 million annually to run in Bengaluru can frequently be replicated in Coimbatore, Vizag, or Indore for $4.5 to $5 million — with comparable talent quality and measurably better retention rates. When the savings are annualized across a five-year lease commitment, the business case becomes difficult to argue against.
This is not a marginal trend. According to industry estimates, more than 60 percent of new commercial office space absorbed in India during 2023 and 2024 was located outside the six primary metropolitan markets. That figure represents a structural shift, not a cyclical fluctuation.
The Cities Attracting the Most Serious Attention
Coimbatore, Tamil Nadu
Coimbatore has long been known as India's textile manufacturing capital, but the city's engineering talent base — fed by a dense cluster of technical universities — has attracted a new generation of corporate interest. Zoho Corporation's decision to anchor significant operations in the city validated what corporate site selectors had been quietly concluding for years. The commercial land market around the Avinashi Road corridor and the emerging IT Special Economic Zone near the airport remains meaningfully undervalued relative to Chennai, despite comparable talent availability.
Vizag (Visakhapatnam), Andhra Pradesh
Andhra Pradesh's decision to designate Vizag as its effective administrative capital following the bifurcation of the state has channeled substantial public investment into the city's infrastructure. The Fintech Valley initiative and the state's aggressive incentive structure for technology companies have attracted early-stage commitments from several multinational firms. Commercial land within the IT corridor near Rushikonda and the HPCL industrial zone is currently priced at a discount that will not persist through the next major announcement cycle.
Indore, Madhya Pradesh
Consistently ranked among India's cleanest and most efficiently governed cities, Indore has developed a corporate reputation that outpaces its public profile among international investors. The Madhya Pradesh government's single-window investment facilitation system has reduced the friction associated with establishing commercial operations, and the Indore Special Economic Zone has attracted anchor tenants whose presence tends to catalyze secondary demand for adjacent commercial land.
The Pre-Announcement Arbitrage Window
The most significant returns in corporate-migration-driven land markets are generated not by investors who respond to official business park announcements, but by those who anticipate them. The pattern is consistent across cycles: a major employer signals intent through subtle indicators — conversations with state investment promotion agencies, site visits by facilities teams, exploratory meetings with local educational institutions about talent pipelines — before any public announcement is made.
Savvy investors learn to read these signals. State government investment summits, while often dismissed as ceremonial, frequently contain forward guidance embedded in MOU signings that precede formal project announcements by 18 to 30 months. The commercial land parcels surrounding the designated zones at these summits represent the clearest pre-announcement entry points available to outside investors.
For US-based investors, the practical challenge is maintaining access to this signal layer from a geographic distance. This is where relationships with established local advisory networks become genuinely valuable rather than merely convenient.
Remote Work Has Permanently Altered the Demand Calculus
The pandemic-era normalization of distributed work arrangements has introduced a variable into corporate location decisions that did not exist with the same force a decade ago. A technology company that once needed to concentrate its India operations in a single metro to facilitate collaboration can now distribute talent across three or four secondary cities, capturing cost arbitrage at each location while maintaining operational coherence through digital infrastructure.
This distributed model is not a compromise — for many corporations, it has become a competitive advantage in talent acquisition. Engineers and analysts in Coimbatore or Vizag who might previously have relocated to Bengaluru for career advancement now have access to multinational employment without surrendering quality of life or proximity to family. The retention implications are significant, and HR-driven considerations are increasingly influencing site selection decisions that were once dominated purely by cost analysis.
The land investment corollary is straightforward: the cities capturing this distributed corporate demand are building a commercial real estate foundation that will sustain appreciation across multiple cycles. The investors who recognize this dynamic before it becomes consensus will capture the most compelling portion of the return curve.
A Contrarian Perspective Worth Holding
The mainstream narrative on Indian real estate investment still gravitates toward Mumbai, Delhi, and Bengaluru — markets that are well-understood, well-covered, and, for that reason, efficiently priced. The opportunity in India's secondary commercial corridors is, by definition, a contrarian one. It requires comfort with complexity, patience with regulatory timelines, and willingness to act on signals that have not yet been amplified by institutional consensus.
For US investors with a tolerance for measured risk and a multi-year investment horizon, that combination of characteristics describes not a liability but a distinct advantage. The corporations are already moving. The land markets have not yet fully responded. That gap is where durable returns are built.